Newsroom
Jeonbuk Bank Launches South Korea’s First Bitcoin-Backed Corporate Loans
12 October, 2026 / News / AI / Tags: jeonbuk, bank, south, collateral, korea
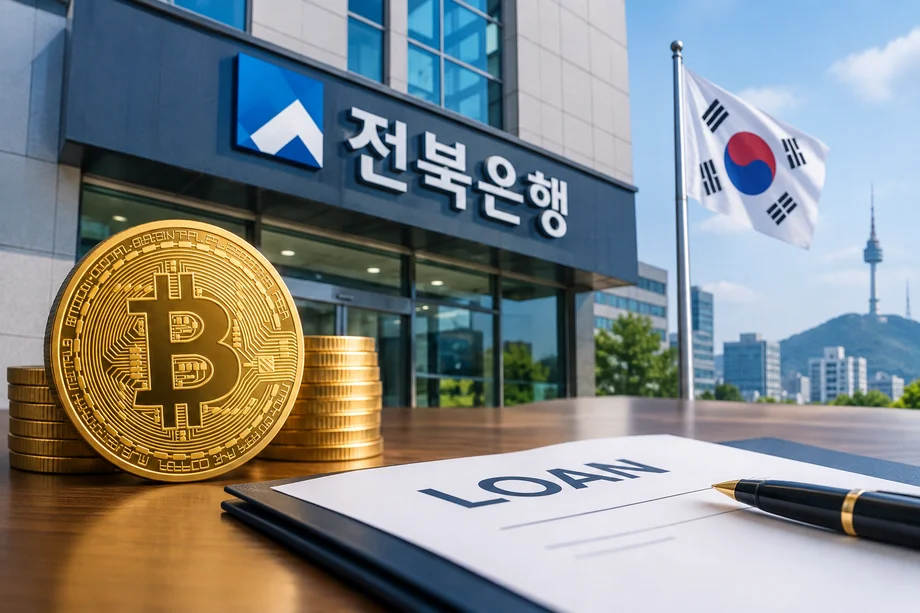
Jeonbuk Bank begins offering won-denominated loans secured by Bitcoin to corporate clients, marking the country’s first such bank product under new enforcement rules
Jeonbuk Bank, a unit of JB Financial Group, has started providing Korean won loans backed by Bitcoin collateral, becoming the first lender in South Korea to introduce this form of financing. The service, which began on a limited basis around October 12, 2026, is available only to registered corporate customers and is restricted to funding business operations such as payroll, supplier payments and other working-capital needs.
Individual retail clients are excluded, and the borrowed funds cannot be used for cryptocurrency speculation. Bitcoin is currently the sole accepted form of collateral. The bank selected the asset because of its leading market capitalization and trading volume, which provide more stable pricing benchmarks than those available for smaller digital assets. Internal stress tests examined performance during sharp price declines and supported its suitability under stressed market conditions.
Third-Party Custody and Valuation Framework
Jeonbuk Bank does not take direct ownership or control of the pledged Bitcoin. Instead, registered virtual asset service providers that meet South Korean regulatory standards hold the collateral. These custodians must maintain Information Security Management System certification, comply with Travel Rule obligations under financial transaction reporting rules, segregate customer assets, meet cold-wallet storage ratios, and carry insurance or maintain reserves as required by the Virtual Asset User Protection Act.
To determine collateral value, the bank uses a proprietary system based on a weighted average of prices drawn from multiple global exchanges, combined with a median measure of market volatility. Officials described this framework as the first of its kind established by a South Korean bank. The approach aims to limit the influence of price swings or disruptions on any single trading platform by relying on publicly available calculation methods and components.
Recovery Process Under Revised Rules
In the event of a borrower default, the bank cannot seize and sell the Bitcoin directly. Under amendments to South Korea’s Civil Execution Rules that took effect on October 1, 2026, recovery requires a court order. The collateral is then liquidated through a public auction or similar court-supervised process, with proceeds applied to the outstanding debt. This structure keeps the bank’s role within conventional lending and enforcement procedures while leaving custody and asset handling to specialized providers.
Jeong Sang-hoon, vice president of the bank’s digital division, said the product applies existing bank lending and collateral management systems to digital assets without requiring direct ownership of the cryptocurrency. The initiative forms the first commercial outcome of President Park Chun-won’s strategy to develop the institution into a crypto-oriented bank.
Broader Context and Future Plans
Similar Bitcoin-backed lending services have been introduced by institutions outside South Korea, including JPMorgan Chase for institutional clients and Swiss bank Sygnum. Jeonbuk Bank already provides real-name deposit and withdrawal accounts to cryptocurrency exchanges, a service unique among the country’s regional banks. A dedicated team of blockchain specialists has conducted proof-of-concept work on payments, remittances and stablecoin services, and the bank is collaborating with external technology partners on an integrated wallet that would combine conventional accounts and digital asset holdings in a single interface.
Details such as interest rates, loan-to-value ratios, maximum loan sizes and the identity of the custody providers have not been disclosed. The bank has indicated it will review operating experience, market demand and regulatory developments before considering expansion to additional digital assets or broader loan purposes.

Disclaimer
This article was generated by AI using information from multiple industry sources. It has not been reviewed or verified by a human editor and may contain inaccuracies, omissions, or misinformation. Readers are encouraged to independently verify any information before making decisions based on its content.Tired of the noise?
Let the bots trade for you.
Trade 24/7, without emotion, with data-driven strategies.
Associated articles

Jeonbuk Bank Deploys Ripple Payments for Faster Business Cross-Border Transfers

Sberbank Prepares Crypto-Backed Corporate Loans as Russia’s New Rules Near
Mirae Asset Targets 150 Trillion Won Digital Asset Business by 2027 via Digital X
Absa Launches First Bank-Backed Digital Asset Custody Service in Africa

Mirae Asset Completes Acquisition of Korbit, Securing Control of South Korean Crypto Exchange
Latest articles
Australia Proposes Extending CFD Rules to Crypto-Settled Derivatives
FSB Flags Untested Stablecoin Risks and Calls for Cross-Border Crisis Planning Ahead of G20
Ripple Criticized Over $250,000 Bounty for Critical XRP Ledger Flaw
Meta Expands AI Agent with Frontier Coding Models and Major Spending Forecast