Newsroom
Central Banks Complete Cross-Border FX Settlement Trial Linking Traditional and Tokenized Systems
14 November, 2026 / News / AI / Tags: meridian, settlement, synchronization, bank, england
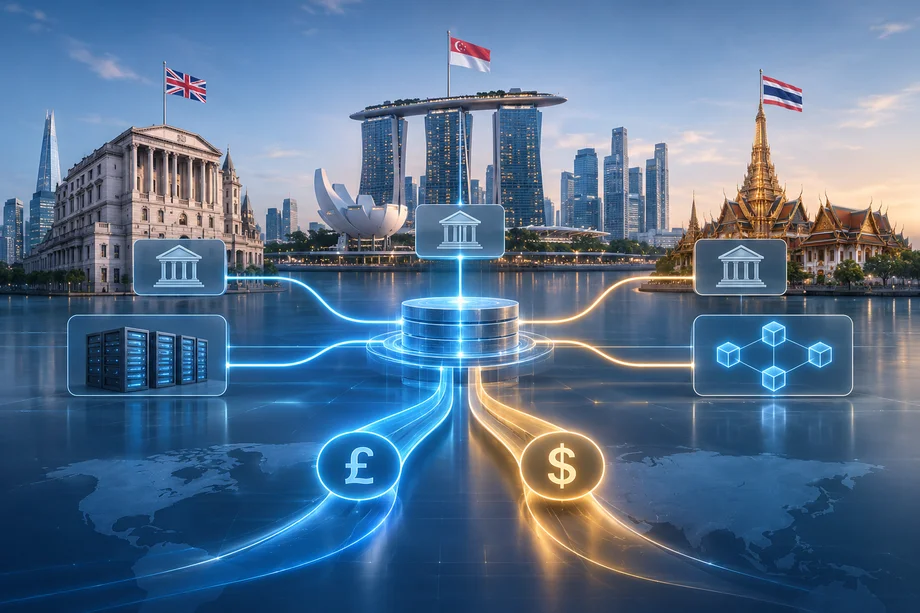
Bank of England, Monetary Authority of Singapore and Bank of Thailand finish Project Meridian FX APAC tests of synchronized payment-versus-payment settlement ahead of 2028 plans
Three central banks have successfully completed trials demonstrating that synchronized foreign exchange settlement can work across traditional real-time gross settlement systems and distributed ledger technology platforms. The Bank of England, the Monetary Authority of Singapore and the Bank of Thailand published the findings from Project Meridian FX APAC on 13 November 2026.
The experiments tested payment-versus-payment settlement, in which both legs of a currency exchange settle simultaneously or not at all, along with multilateral net settlement. A prototype Synchronization Operator developed by technology firm Partior coordinated the transfers across the three distinct test environments.
Trial Design and Systems Tested
Project Meridian FX APAC built on earlier Meridian FX work and expanded the scope to a wider range of currencies, technologies, infrastructures and time zones. The Bank of England used its Synchronisation Lab, a traditional account-based real-time gross settlement test environment. The Bank of Thailand contributed Project SAN, a centralized tokenized payment system with an interoperability layer. Singapore provided its SGD Testnet, a distributed ledger technology platform supporting wholesale central bank digital currency with participant-controlled wallets.
The Synchronization Operator matched settlement instructions, coordinated the reservation of funds, monitored readiness and triggered final settlement. Tests covered both bilateral payment-versus-payment trades and multilateral netting, in which overlapping obligations among multiple participants are offset to reduce the liquidity each bank must hold.
The trials confirmed that atomic settlement remains possible across systems with materially different architectures, provided core synchronization capabilities exist. Where capabilities differed, the operator sometimes needed to perform additional functions, increasing integration complexity.
Liquidity Benefits and Technical Limits
Multilateral net settlement proved technically achievable. By coordinating a common set of eligible transactions and ensuring liquidity remained reserved across all systems until completion, the approach reduced the amount of funds participants needed to maintain while still preserving the all-or-nothing settlement principle.
The experiments ran entirely in simulated environments. They did not involve live production systems, real commercial counterparties or actual money. Officials noted that longer outages, non-overlapping operating hours and true production volumes were outside the scope of the tests. Technical differences between the platforms also expanded the range of responsibilities assigned to the operator in some scenarios.
Policy and Regulatory Considerations
Alongside the technical work, a policy workstream examined the conditions required for a live cross-border service. Key issues include settlement finality under different national legal frameworks, the governance and oversight of any Synchronization Operator, liability allocation when errors occur, and the form of regulatory cooperation needed between authorities.
The Reserve Bank of Australia and Bangko Sentral ng Pilipinas participated as observers and contributed perspectives. The three reports published with the findings—an executive summary, a technical report and a policy report—make clear that technical coordination alone does not create legally binding settlements across jurisdictions.
Path Toward 2028 Implementation
The Bank of England stated that the trial results will inform the design of a live synchronization interface it plans to introduce in 2028. Neither Singapore nor Thailand has announced an equivalent operational commitment or timeline.
The work sits against a backdrop of substantial foreign exchange settlement volumes that still carry residual risk. Industry surveys have shown that a material share of daily FX obligations continues to settle without payment-versus-payment protection, leaving counterparties exposed to the possibility that one side of a trade completes while the other does not.
Project Meridian FX APAC demonstrates one practical route to narrowing that exposure by linking heterogeneous central bank systems without requiring them to adopt a single common technology. The next phase of work will need to address the remaining operational, legal and governance questions before any production service can be offered.
Disclaimer
This article was generated by AI using information from multiple industry sources. It has not been reviewed or verified by a human editor and may contain inaccuracies, omissions, or misinformation. Readers are encouraged to independently verify any information before making decisions based on its content.Tired of the noise?
Let the bots trade for you.
Trade 24/7, without emotion, with data-driven strategies.
Associated articles
Singapore, Malaysia and Thailand Central Banks Expand BLOOM for Cross-Border Digital Money Settlement
Bank of England Selects Consortium for Digital Pound Trade Finance Trials
Hong Kong Extends Tokenized Deposit Settlements to Round-the-Clock Operation
Visa Partners with Nium for Seven-Day Stablecoin Settlement Pilot in Singapore
Malaysia Central Bank Unveils Tokenized Bond Platform Enabling Round-the-Clock Settlement
Latest articles
Ethereum Draft Introduces Sponsored Batch Proofs for Shared Verification
dYdX Governance Vote Advances Injective USDC as Cosmos Collateral Standard
House Oversight Chair Pushes Restrictions on Officials Trading Prediction Markets
Cardano Founder Denies Promising ADA Price Gains as Token Trades Near Multi-Year Lows